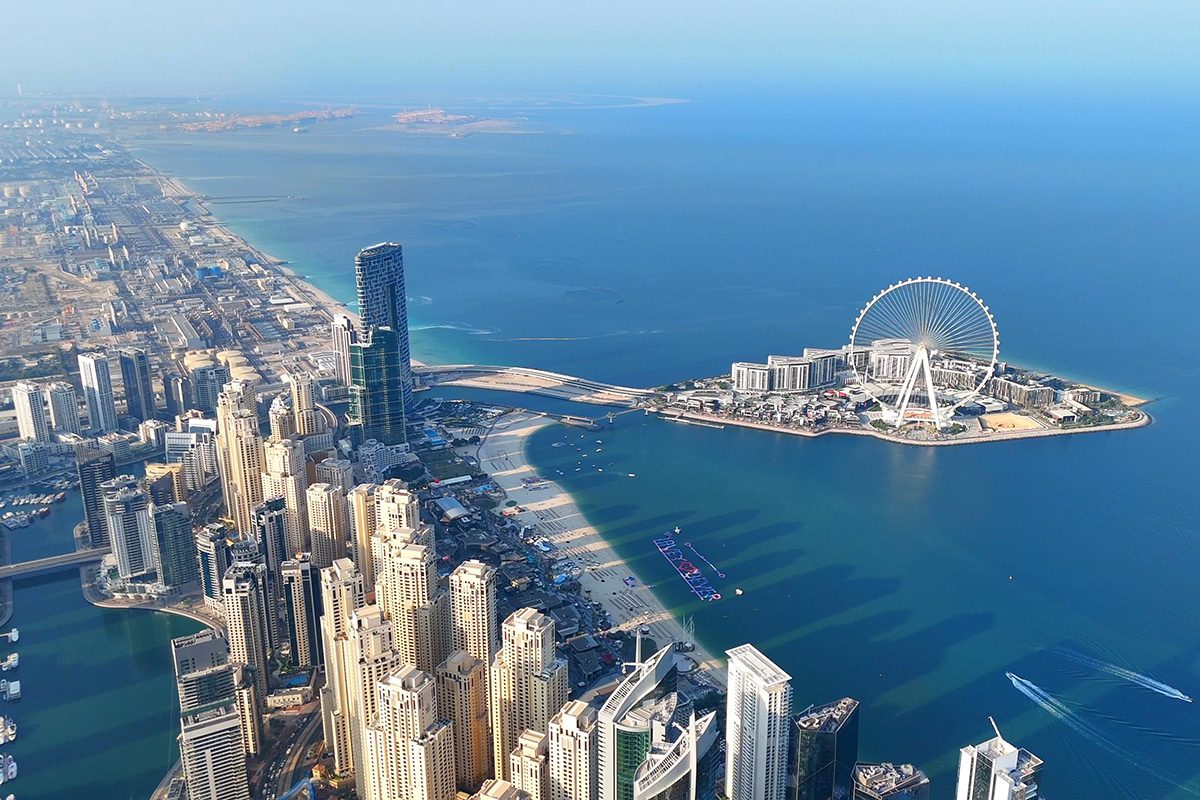
The UAE real estate market demonstrated resilience during the second quarter of 2026 despite a challenging macroeconomic environment and persistent regional uncertainties. Commercial real estate remained the strongest-performing segment, supported by robust occupier demand and a limited supply of office and industrial space.
CBRE reported that Dubai’s office rents rose 13 per cent year-on-year, while office occupancy in Abu Dhabi reached around 96 per cent. However, softer demand continued to affect the tourism, retail and certain residential segments.
In its UAE Real Estate Market Review for the second quarter of 2026, CBRE Middle East stated that commercial property fundamentals remained stable, even as non-oil sectors, including tourism and retail, experienced weaker performance.
The consultancy noted that ongoing geopolitical tensions have continued to impact domestic economic activity, leading to a downward revision of the UAE’s economic growth forecast for 2026.
CBRE now expects the UAE economy to contract by 0.04 per cent in 2026, reflecting the effects of disruptions across trade, tourism, aviation and other consumer-focused industries. The firm, however, anticipates a strong economic rebound in 2027 as regional conditions improve.
Dubai’s office sector continued to record solid performance, driven by sustained occupier demand and a shortage of available high-quality office space.
Average office rents in Dubai increased 13 per cent year-on-year during the second quarter, while prime office rents recorded a stronger annual growth of 16 per cent.
Office occupancy levels remained exceptionally strong at approximately 94 per cent, highlighting the continued scarcity of Grade A office space across the emirate.
Demand remained concentrated in major commercial hubs and free zones, including DIFC, TECOM and DMCC, where strong pre-leasing activity continues to absorb a substantial share of upcoming office supply before project completion.